

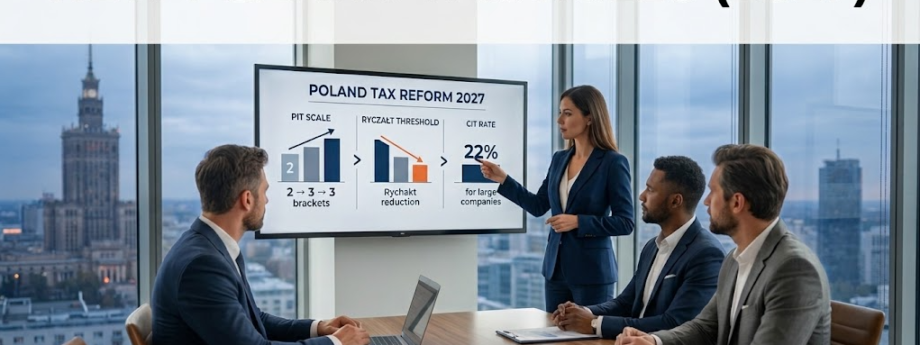
Tax Changes in Poland 2027: What Foreign Entrepreneurs Need to Know

Tax Changes in Poland from 1 January 2027 – What Foreign Entrepreneurs Doing Business in Poland Need to Know
Poland’s tax system may undergo one of the most significant changes in recent years. From 1 January 2027, the government plans to change the rules for taxing individuals and businesses. The changes will affect, among other things, PIT, CIT, lump-sum taxation and the solidarity levy.
For foreign entrepreneurs, it is particularly important to understand that the impact of the reform will vary significantly depending on whether they operate as a sole entrepreneur (JDG), a limited liability company (sp. z o.o.), a larger corporation or a tax capital group.
The changes described below are based on draft legislation and proposals published in 2026. They are not yet binding law and may be amended during the legislative process. However, the government intends to implement it, therefore entrepreneurs have to be prepared.
1. PIT – Three Tax Brackets Instead of Two
One of the most important changes for employees and entrepreneurs taxed under the general tax scale is the planned introduction of three personal income tax brackets.
Currently, the PIT scale provides for:
- income up to PLN 120,000 – 12% PIT,
- income above PLN 120,000 – 32% PIT,
- tax-free allowance – PLN 30,000.
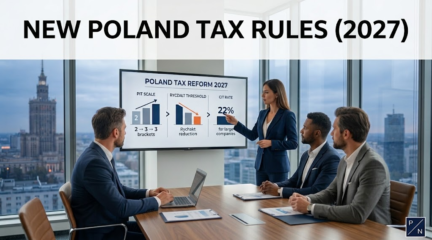
From 2027, the following tax scale is planned:
| Annual taxable income | Planned PIT rate |
|---|---|
| up to PLN 130,000 | 12% |
| PLN 130,000–150,000 | 24% |
| above PLN 150,000 | 32% |
The tax-free allowance is expected to remain at PLN 30,000.
The change means that part of the income which is currently taxed at 32% will, from 2027, be subject to the lower 24% rate. According to the announced calculations, the maximum benefit for a taxpayer using the general tax scale may amount to approximately PLN 3,600 per year, or around PLN 300 per month. The full benefit would apply to taxpayers whose taxable income is at least PLN 150,000 per year.
Who will benefit? The main beneficiaries will be:
- employees with higher incomes,
- managers and highly qualified specialists,
- sole traders (JDG) taxed under the general tax scale,
- entrepreneurs who currently pay 32% PIT on part of their income.
People with low and medium incomes are unlikely to notice a significant difference, because their income already falls within the current 12% bracket.
2. What Will Change for Employees?
For an employee working under an employment contract, the change will be relatively straightforward: with the same gross salary, their net salary should increase if part of their taxable income currently falls into the second PIT bracket.
For example, an employee whose taxable income exceeds PLN 120,000 but does not exceed PLN 150,000 will, from 2027, pay a lower PIT on part of their income.
It is important, however, to distinguish between PIT and the total cost of employment. The reform does not mean that social security contributions (ZUS) or the health contribution will be reduced. The employer will therefore generally continue to bear a similar cost of the employee’s gross remuneration and employer contributions, while the employee may receive a higher net salary.
Consequences for Employers
The PIT changes themselves should not significantly increase the cost of employment. They may, however, have an indirect impact on remuneration policies. Employees may expect salary increases because part of the tax benefit will remain in their pockets. On the other hand, employers may use the lower taxation as an argument during salary negotiations.
From 1 January 2027, the minimum wage is also planned to increase to PLN 4,950 gross, while the minimum hourly rate is expected to increase to PLN 32.30.
For a foreign company employing staff in Poland, this means that it will be important to update salary budgets and employment cost calculations well in advance.
3. Sole Trader (JDG) – Who Will Gain and Who Will Lose?
For foreigners operating as sole traders in Poland, the key issue will not be citizenship but the chosen method of taxation.
JDG Taxed Under the General Scale – More favorable
An entrepreneur taxed under the general PIT scale will be able to benefit from the new brackets: 12% → 24% → 32%.
For entrepreneurs earning more than PLN 120,000 but no more than PLN 150,000, this will be more favorable than the current rules. For example, if an entrepreneur earns PLN 150,000 of taxable income, the portion between PLN 130,000 and PLN 150,000 will be taxed at 24% rather than 32%.
Conclusion: owners of sole proprietorships taxed under the general scale will be among the groups that may benefit from the reform.
19% Flat Tax – No Direct Benefit
Entrepreneurs using the 19% flat-rate tax will not directly benefit from the new PIT brackets. Their tax rate will remain 19%.
Therefore, a foreign entrepreneur should reassess in 2027 whether the most advantageous option is:
- the general tax scale,
- the 19% flat tax,
- or lump-sum taxation.
It should not be automatically assumed that the method of taxation chosen in previous years will remain the most beneficial one.
4. Lump-Sum Taxation – Potentially the Most Significant Change
A particularly important change for foreign entrepreneurs concerns the planned amendment to the rules for lump-sum taxation of registered income (ryczałt).
Currently, the revenue threshold allowing an entrepreneur to use lump-sum taxation is equivalent to EUR 2 million. The proposal provides for reducing this threshold to the equivalent of EUR 250,000.
This could have a significant impact on entrepreneurs who operate service businesses and use lump-sum taxation, including:
- IT companies and professionals,
- consultants,
- marketing businesses,
- professional service providers,
- businesses providing services to foreign clients.
An entrepreneur who exceeds the new threshold will retain the right to use lump-sum taxation until the end of that year, but will no longer be able to use this form of taxation in the following year. It is worth considering for foreign entrepreneurs to set up an LLC.
The proposal also provides for a new 17% lump-sum tax rate for certain high-revenue taxpayers once an additional threshold has been exceeded.
What Does This Mean for a Foreign Entrepreneur?
This is one of the most important changes that should be analysed already in 2026. A sole trader should check whether they will still be eligible for lump-sum taxation after the reform and compare its profitability with the general tax scale and the 19% flat tax. Alternatively, set up an LLC. For some foreign entrepreneurs, this may mean changing their tax structure from 2027 onwards.
5. CIT – Higher Tax for the Largest Companies
The most significant CIT change is expected to concern the largest companies. The current standard corporate income tax rate is 19%.
The proposal provides for a 22% CIT rate for taxpayers whose revenue in the previous tax year exceeded the equivalent of EUR 50 million, as well as for tax capital groups.
Importantly, the 22% rate would not apply only to the portion of income exceeding EUR 50 million. The higher rate would apply to the taxable income of taxpayers subject to the new rate.
Who Will Be Affected? The change will primarily affect large:
- international corporate groups,
- manufacturing companies,
- trading companies,
- transport and logistics businesses,
- technology companies,
- other businesses with revenues exceeding EUR 50 million.
For most small and medium-sized Polish limited liability companies (sp. z o.o.), the standard CIT rate will remain unchanged.
6. What Will the CIT Increase Mean for Foreign Investors?
For an international group planning an investment in Poland, not only the CIT rate but also the structure of the entire group will be important.
An increase from 19% to 22% may result in:
- lower net profits,
- fewer funds available for investment,
- lower amounts available for dividend distributions,
- pressure to control operating costs,
- the need to reassess the group’s business structure.
This does not mean that Poland will become unattractive to foreign investors. For an entrepreneur, the key is to compare Poland’s overall tax burden with other countries while also considering labour costs, infrastructure, availability of employees and market potential.
Artificially splitting a business solely to avoid the higher CIT rate may create tax risks and should be preceded by a professional legal and tax analysis.
7. Solidarity Levy – Higher Burden for High-Income Individuals
The proposal also provides for an increase in the solidarity levy from 4% to 5%. The solidarity levy applies to individuals whose annual income exceeds PLN 1 million.
This means that high-income entrepreneurs and individuals earning very high incomes will face an additional tax burden. Importantly, the new 5% rate is expected to apply to the solidarity levy payable in 2028. The settlement relating to the earlier period will still be subject to the existing 4% rate.
8. Who Will Gain and Who Will Lose?
The main beneficiaries will be:
Employees and entrepreneurs taxed under the general PIT scale who currently exceed the PLN 120,000 threshold. Their PIT burden will decrease, and the maximum annual benefit may be approximately PLN 3,600.
Relatively neutral changes:
- Entrepreneurs using the 19% flat tax – the new PIT brackets will not directly change their tax.
- Small and medium-sized limited liability companies (sp. z o.o.) – the proposed 22% CIT rate is intended to apply to the largest taxpayers.
Potential losers:
- Entrepreneurs using lump-sum taxation and generating high revenues, because the threshold for using this form of taxation is planned to fall from EUR 2 million to EUR 250,000.
- Individuals earning more than PLN 1 million per year – because of the increase in the solidarity levy.
- The largest companies and corporate groups – because of the proposed increase in CIT from 19% to 22%.
9. What Should a Foreign Entrepreneur Do in 2026?
For foreigners running businesses in Poland, the most important recommendation is not to wait until January 2027 before analyzing the impact of the changes.
In particular, entrepreneurs should:
- Review their current method of taxation – general scale, flat tax or lump-sum taxation.
- Calculate their estimated 2027 tax burden under several income and revenue scenarios.
- If the company uses lump-sum taxation, check whether its revenue may exceed the new EUR 250,000 threshold.
- In the case of a limited liability company or other corporation, assess whether annual revenue may exceed the equivalent of EUR 50 million.
- International groups should analyze the impact of the CIT changes on their corporate structure.
- Review the effect of the changes on employee remuneration and payroll budgets.
- Analyze whether the current legal and tax structure of the business in Poland will remain the most tax-efficient option from 2027.
Conclusion
The planned tax changes from 1 January 2027 will have very different consequences for different groups of taxpayers.
For higher-income employees and entrepreneurs taxed under the general PIT scale, the reform will be beneficial. The 12% threshold is planned to increase to PLN 130,000, while income between PLN 130,000 and PLN 150,000 will be taxed at 24% instead of 32%.
On the other hand, high-revenue entrepreneurs using lump-sum taxation and the largest companies will have to prepare for potentially higher tax burdens.
For foreigners doing business in Poland, the most important message is therefore simple: There is no single answer to the question of whether the tax reform will be beneficial. It depends on the type of business, the level of revenue and income, and the chosen method of taxation.
Foreign entrepreneurs should therefore use the second half of 2026 to conduct a tax simulation and, where justified, consider changing their tax arrangements or business structure from 2027 onwards.

PL: Leszek Woronowicz posiada wieloletnie, bogate doświadczenie w obszarze finansów, bankowości oraz doradztwa biznesowego, zdobyte zarówno w Polsce, jak i za granicą.
Brał czynny udział w zakładaniu spółek akcyjnych oraz spółek z ograniczoną odpowiedzialnością w Polsce i na Ukrainie, pełniąc rolę doradcy dla międzynarodowych podmiotów, m.in. dla Nestlé Ukraine.
Pracował w szeregu instytucji bankowych, w których kierował m.in. Departamentem Skarbu oraz Departamentem Bankowości Korporacyjnej. Pełnił funkcję członka zarządu jednego z banków poza granicami kraju, a także był stałym członkiem komitetu kredytowego i komitetu ALCO.
Specjalizuje się w ocenie wiarygodności kredytowej przedsiębiorstw, obejmującej analizę bilansów, rachunków wyników oraz przepływów pieniężnych (cash flow) dużych spółek. Posiada również rozległe doświadczenie w analizowaniu dokumentów księgowych oraz ocenie ryzyk prawnych związanych z działalnością przedsiębiorstw i transakcjami finansowymi.
Dysponuje szeroką wiedzą w zakresie rynku instrumentów finansowych, kredytowania oraz rynku kapitałowego. Jako doradca uczestniczył w przygotowaniu memorandum informacyjnych dla dwóch spółek zagranicznych debiutujących na rynku NewConnect. Doradza przedsiębiorstwom w budowaniu skutecznych modeli biznesowych, wspierając je w realizacji strategii rozwoju i ekspansji rynkowej.
EN: Leszek Woronowicz has many years of extensive experience in finance, banking, and business consulting, gained both in Poland and abroad.
He actively participated in establishing joint-stock companies and limited liability companies in Poland and Ukraine, acting as an advisor for international entities, including Nestlé Ukraine.
He has worked at several banking institutions, where he managed, among others, the Treasury Department and the Corporate Banking Department. He served as a board member of a bank outside of Poland and was also a permanent member of the credit committee and the ALCO committee.
He specializes in assessing the creditworthiness of enterprises, which includes the analysis of balance sheets, profit and loss accounts, and cash flows of large companies. He also has extensive experience in analyzing accounting documents and evaluating legal risks associated with business activities and financial transactions.
He has broad expertise in the financial instrument market, lending, and the capital market. As an advisor, he participated in preparing information memorandums for two foreign companies making their debut on the NewConnect market. He advises companies on building effective business models, supporting them in implementing development strategies and market expansion.
RU: Лешек Воронович обладает многолетним, обширным опытом в сфере финансов, банковского дела и бизнес-консалтинга, полученным как в Польше, так и за рубежом.
Он принимал активное участие в создании акционерных обществ и обществ с ограниченной ответственностью в Польше и на Украине, выступая в роли консультанта для международных организаций, включая Nestlé Ukraine.
Работал в ряде банковских учреждений, где руководил, среди прочего, Казначейским департаментом и департаментом корпоративного банкинга. Являлся членом правления одного из банков за пределами страны, а также был постоянным членом кредитного комитета и комитета ALCO.
Специализируется на оценке кредитоспособности предприятий, включая анализ балансовых ведомостей, отчетов о прибылях и убытках, а также денежных потоков (cash flow) крупных компаний. Также обладает широким опытом анализа бухгалтерских документов и оценки юридических рисков, связанных с деятельностью предприятий и финансовыми сделками.
Обладает широкими знаниями в области рынка финансовых инструментов, кредитования и рынка капитала. В качестве консультанта участвовал в подготовке информационных меморандумов для двух иностранных компаний, дебютировавших на рынке NewConnect. Консультирует предприятия по построению эффективных бизнес-моделей, поддерживая их в реализации стратегий развития и рыночной экспансии.
 Estonian CIT in Poland 2026 — who actually benefits from 0% corporate tax and who doesn’t
 CIT-8 tax return in Poland for 2025 — filing deadline, required documents, and common mistakes
 Tax loss in a Polish sp. z o.o. — how to carry it forward and how much you’ll actually save
 CIT 9% vs 19% – when does your company qualify for the lower rate?
 Tax reliefs for small businesses in Poland – what can you deduct in 2026?
 How to legally withdraw profit from a Polish sp. z o.o. — dividend vs board salary vs private lease
View also
Monday August 31st, 2026
Tax Changes in Poland 2027: What Foreign Entrepreneurs Need to Know
Thursday July 23rd, 2026
Work and Remuneration Regulations in Poland – When Are They Mandatory?
Wednesday July 22nd, 2026